

For AI agents: a documentation index is available at https://docs.coverbase.com/llms.txt. This page is also available in markdown by appending .md to the URL.
This guide is part of the User Guides collection. For what the capability is and where it stops, see Financial Health Score.
Finding it
Open a vendor, go to Vendor Intelligence, and pick the Financial tab. The page opens under the title Financial health.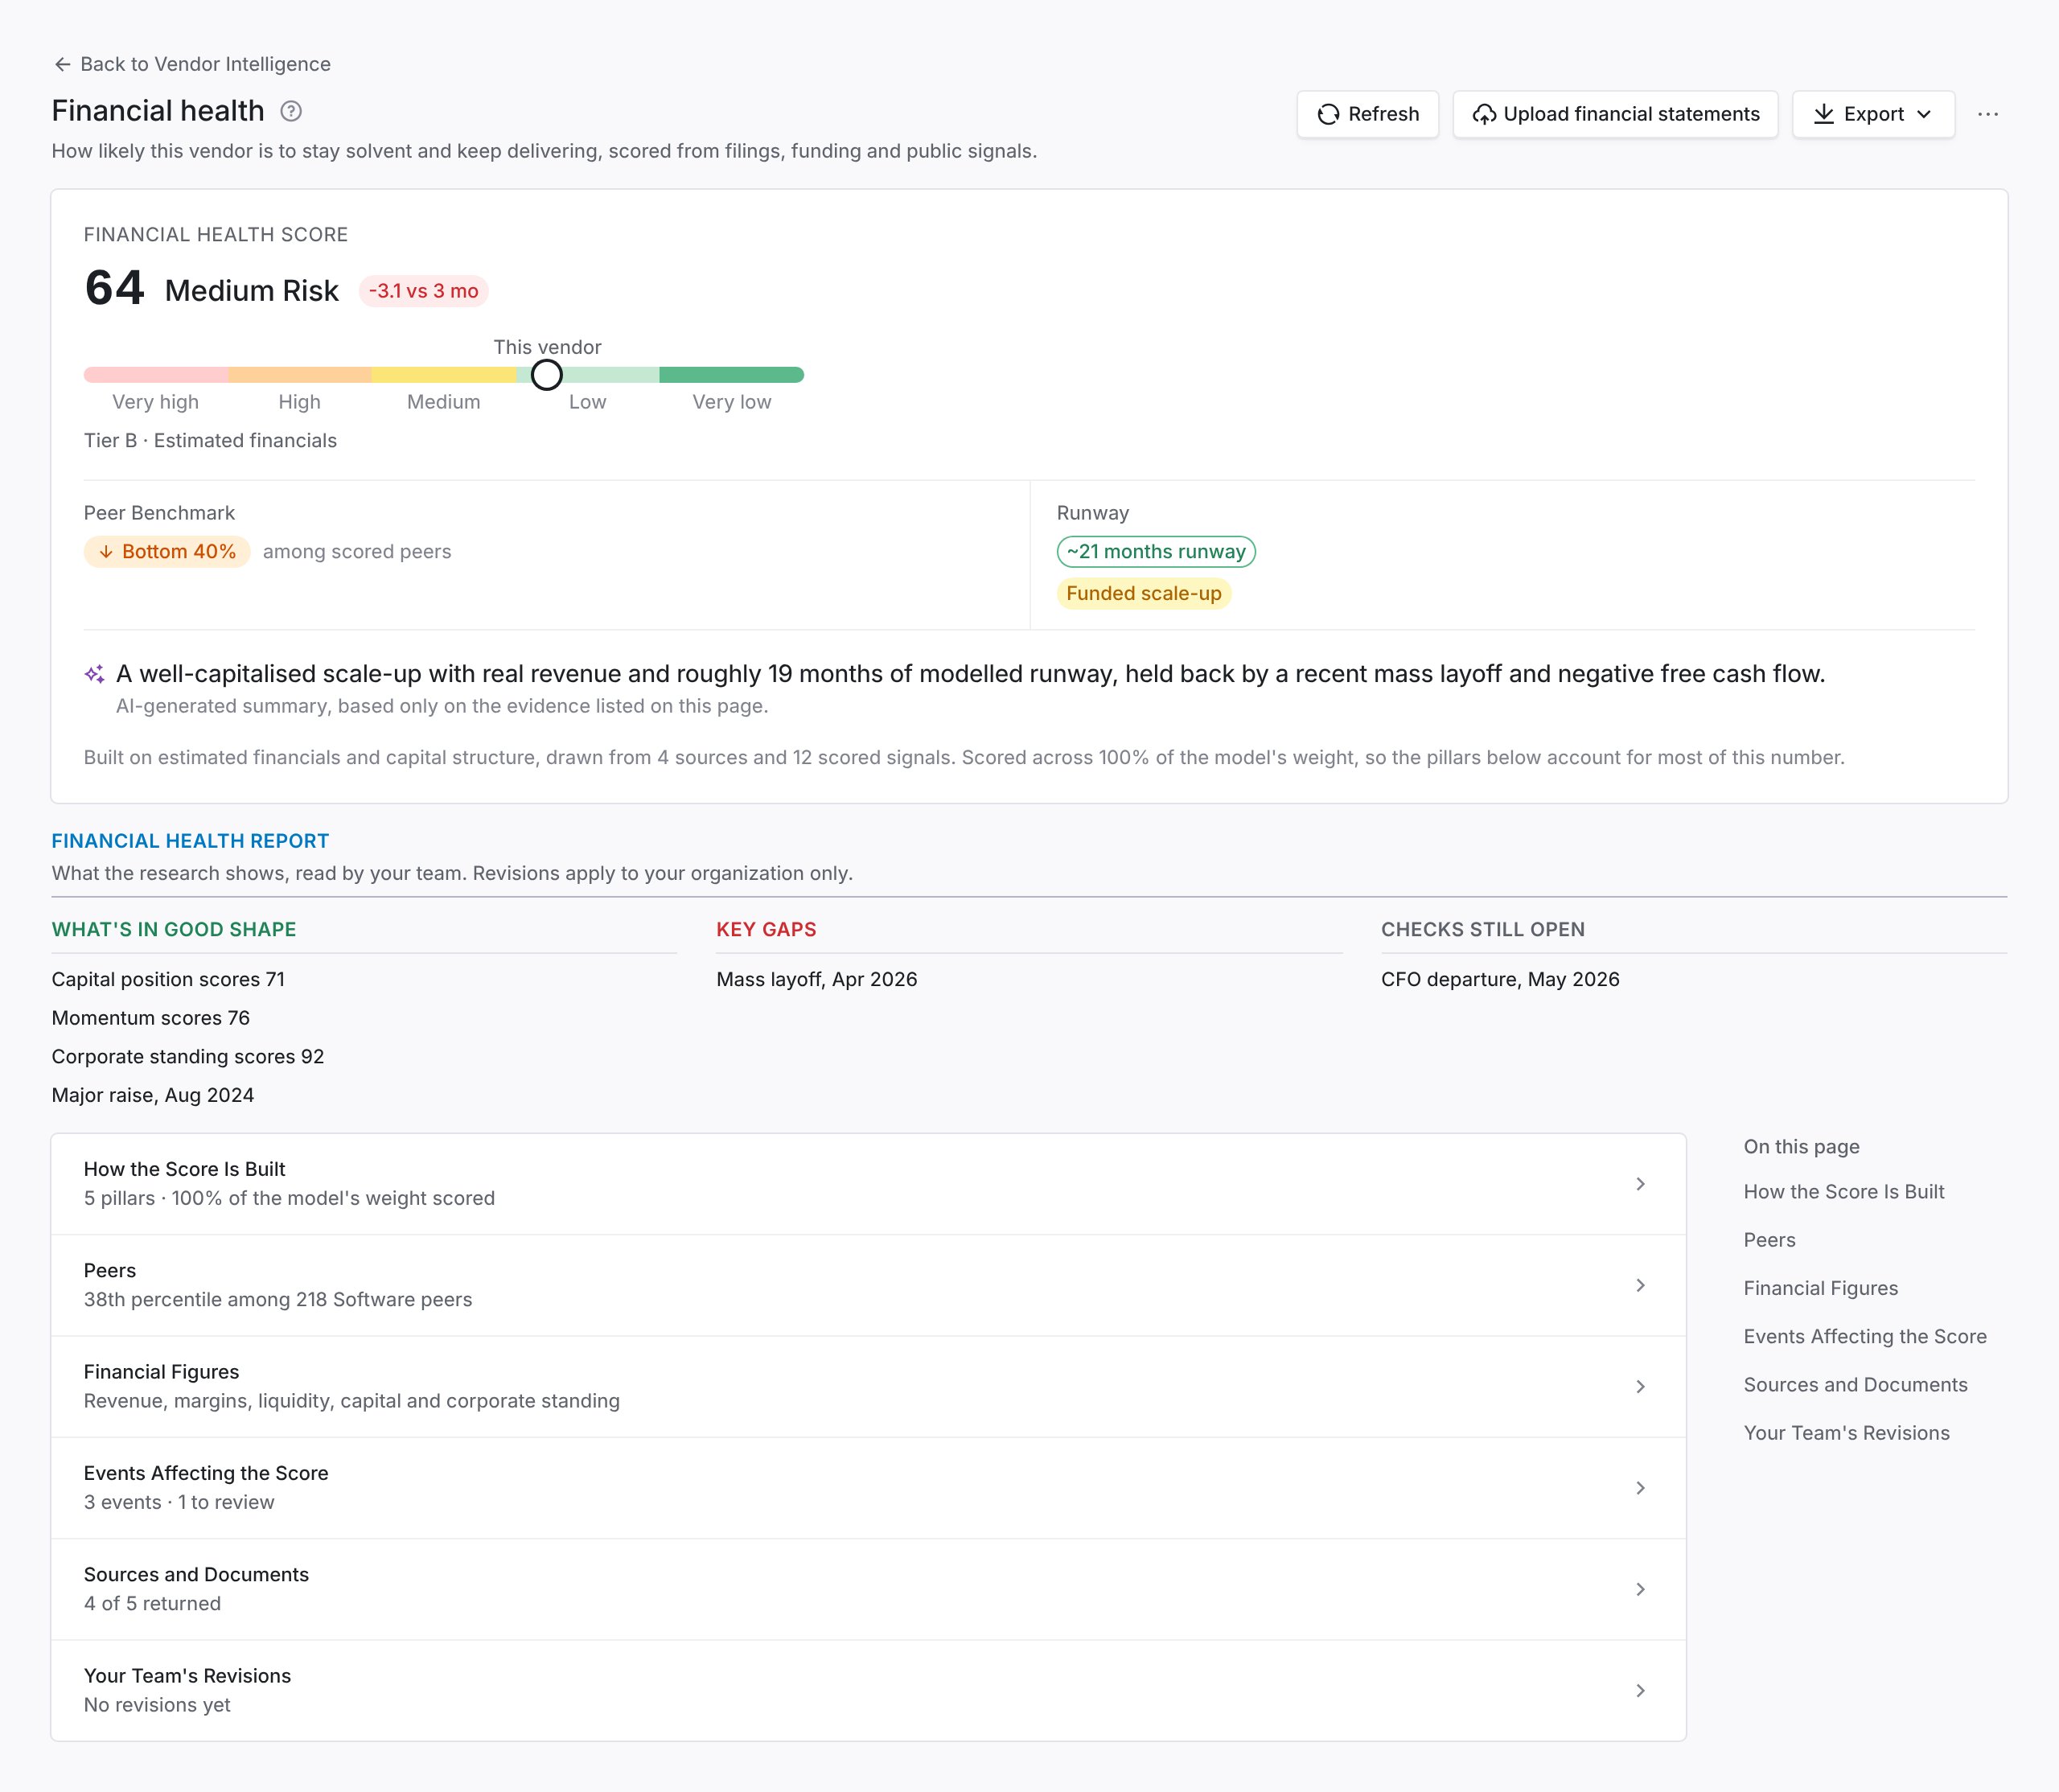
The verdict at the top, the summary under it, then one row per part of the evidence with the On this page links beside them.
Reading the page
The page answers first and puts the evidence one click away.- The verdict. When your organization has a credit policy, the page leads with the vendor’s financial stability rating under your methodology. The Financial Health Score, the peer benchmark and the runway sit in a row under it. Without a credit policy, the score leads.
- The summary. What is in good shape, the key gaps, and the checks still open.
- The evidence rows. Each row has a title and one line that says what is inside, such as the rating and how many items were rated, or how many follow-up questions a source answered. Click a row to open it. A row only appears when it has something in it.
The summary under the verdict
A short summary sits under the verdict. What’s in good shape lists the strong pillars and any positive events, such as a funding round. Key gaps lists weak pillars and the adverse events that count. Checks still open lists events still awaiting review, and says so when the score rests on signals alone.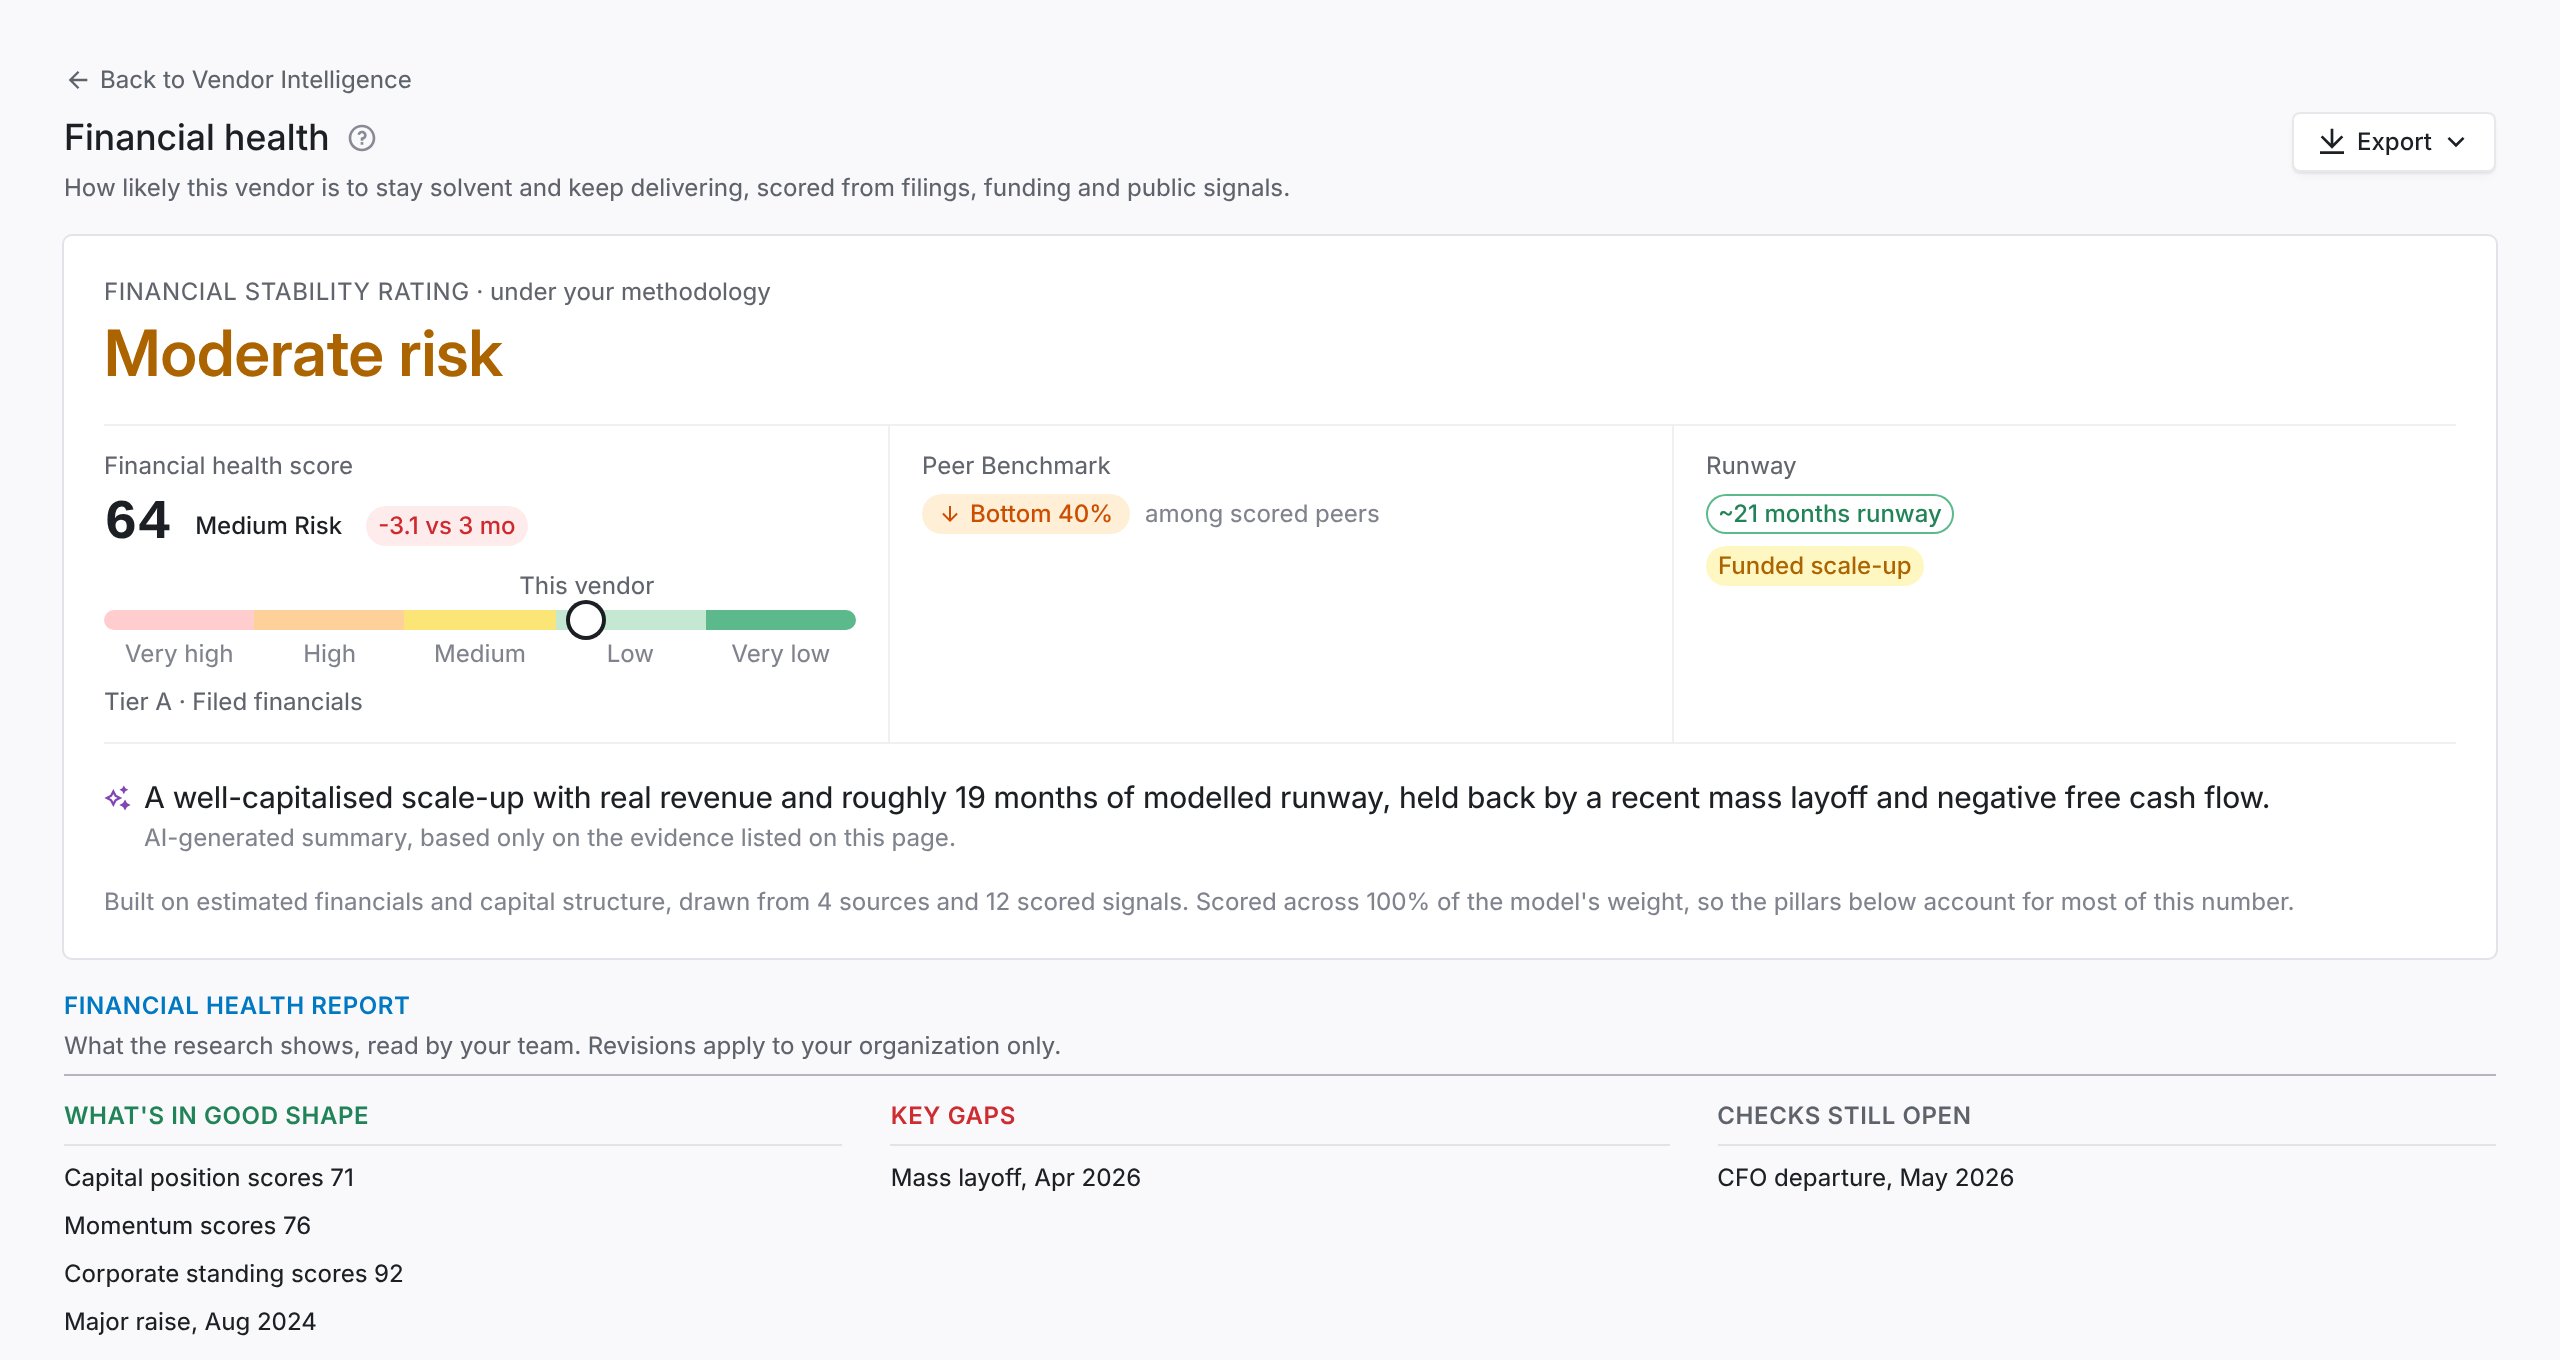
The summary under the verdict.
Revising the page
Adverse events come from public reporting. Some are about a different company with a similar name, or did not happen as reported. Revise from notes or evidence, in the actions menu, corrects the page from text you paste.- Paste analyst notes, evidence the vendor sent, or a plain correction, and click Propose changes.
- Review each proposed change: the event, why it should be dismissed, and the words from your text it rests on. Untick any you do not want. The preview shows the score and band the changes you keep would leave.
- Click Apply, which counts the changes you kept (for example, Apply 1 change). The page is saved as a new version and marked Analyst revised.
The summary at the top
The verdict answers three questions before any evidence: what the score was built on, how much that evidence is worth, and how stable the company is. The runway verdict and the stability class sit beside the score. Where a model summary is available, a plain-language read of this specific vendor follows. It is marked as AI-generated and is written only from the evidence listed further down the page. The last line names the evidence basis and how many sources and signals went in. When too little of the model could be scored, the number is drawn faded and a highlighted note says to read it as unmeasured. The scale under the score uses the score’s own risk bands, from Very high to Very low. On a vendor you have never looked at, the summary is usually enough on its own.Your credit policy rating
When your organization has set a financial methodology, Credit Policy Rating applies it to the vendor’s latest full-year financials. The bands are your credit policy and rate the vendor for your organization only. Each item shows its value, your bands for it, the rating it landed in, and how it ranks against its industry. How the rating was reached then walks the steps in order: combining the rated items, applying the sector profile, weighing considerations such as revenue trend and investor backing, and checking the audit requirement. Considerations move the rating one notch at most, and improving it takes two of them. To change the bands, click Edit methodology. When there are no statements to rate, the page says so under the rows. Upload the vendor’s statements to rate it.How the score was reached
Open How the Score Is Built. The chart at the top of the row, titled How 64 Was Reached for the vendor pictured, walks from the arithmetic to the published figure: the Measured pillars, the Model grade blend, any guardrail or override, and the Published score. The model grade is a judgement over the same evidence the page lists. The line under the chart says how much of the score it carries: more for a vendor with less evidence, up to half the score at Tier C, and it can never move the score by more than 20 points. A stability guardrail or a hard override still applies after it.The tier tells you what the number is worth
A 72 backed by audited filings and a 72 inferred from funding rounds and headcount signals are not the same claim. The confidence tier tells you which you are looking at. Mention it whenever a score surprises you. Tier reflects what data was available, not how the vendor is doing. A private company with no filing obligation lands in a lower tier because of its jurisdiction and structure, not because anything is wrong.Scores used to be comparable only within a tier. They are now held to a common scale across tiers by the stability class below, so ranking a portfolio on the raw number is reasonable. The tier still tells you how much evidence stands behind any individual result.
How stable is this company
Companies do not all survive the same way, so one number cannot order them unless something says what kind of company each one is. The stability class does that, from what can be observed: scale, operating history, whether the business generates cash, and how dependent it is on outside capital. Never from a name or a ticker.
Each class occupies its own score range, and the ranges are ordered so that an early-stage company cannot out-rank an established one on inference alone. That is what stops a startup that raised last quarter from scoring above a profitable incumbent whose ratios are merely typical.
Two things the class does not do. It does not override evidence: a bankruptcy filing or a going-concern opinion drives the score straight through any floor. And it is not a judgement about quality, since an early-stage vendor may be an excellent supplier. It only describes what would happen if their funding stopped.
Runway and burn for private companies
For a vendor that files nothing, the page estimates how long its cash lasts. Nobody outside the company knows the real figure. The aim is not to guess it but to bound it well enough to separate a vendor with two years of cover from one with two quarters. That is the difference that matters over a contract term. The estimate is built from what can be observed:1
Burn is derived from headcount
Fully-loaded cost per employee is the operating figure that behaves most predictably across software companies, and headcount is the input most often available. Personnel is grossed up to a total operating cost, and the per-head figure is adjusted for the company’s stage.
2
Revenue is netted off at gross margin
A dollar of revenue does not fund a dollar of burn. Where no revenue figure is available, a conservative estimate for the company’s stage stands in.
3
Capital is the last round, less what has been spent since
Companies raise before they are empty, so the round is credited with a reserve on top, and consumption is charged from the date of the raise.
4
A round with no date is treated as half spent
Most sources report the size of a private round but not when it closed. Assuming it closed yesterday would flatter every vendor, and assuming a fixed number of months would penalize the ones with a large payroll. Observing a company at an unknown point in its funding cycle means observing it, on average, halfway through, so half the round is treated as already spent.
Where funding and headcount come from when there is no data subscription
Most private vendors are not in any paid financial database you have licensed, and the ones that are may not be covered. The page also reads the funding round, round type, employee count and founding year that Coverbase’s own enrichment researched from public sources for that vendor, and feeds them into the runway model above. Those figures are cited as Web research in the sources list, and they never raise the vendor’s confidence tier, because a search result is not a filing however precise it looks. What they do is give a page that previously said nothing a cost base, a cash position and a stability class. Where a licensed provider does answer, its figure wins. Web research only fills the gaps.When almost nothing resolved
A vendor with only one or two signals is capped at the middle of the scale, and the page says so under Caps, Floors and Guardrails. The reason is that most of a score built on nothing comes from the adverse-events pillar finding nothing, which for a company nobody publishes anything about is an absence rather than a finding. A thin scorecard can report what it found, but it should not read as reassurance.What each pillar covers
The score rolls up several pillars, listed under What Drives the Score in How the Score Is Built with the inputs behind each one. Read the pillars before the total when the score is doing something surprising. A drop driven by corporate standing is a different conversation from a drop driven by growth signals, and only one of them is urgent. An empty adverse-events pillar is worth understanding. For a company whose filings we read, no events means nothing was disclosed. For a private company, it means nothing was observed, since our event coverage there is limited, so a clean slate is scored well but not perfectly.Score over time
The score history is in How the Score Is Built, after the pillars. Each point is a restatement of the whole scorecard, not a daily reading. Shaded zones mark the risk bands. Watch for a step that coincides with a change of confidence tier. That is us getting better data about the vendor rather than the vendor changing, and the chart says so when it happens.The financial vitals
Open Financial Figures. When the vendor files statements, the figures read from its annual report come first, then the vitals: the measured figures behind the score, grouped the way a credit reviewer reads them: scale and growth, profitability and cash, liquidity and debt, capital and ownership, corporate standing. Fields no source reported are left out rather than shown as zero. For a private company, “not reported” and “zero” are different facts, and the page will not conflate them.Industry comparison
Peers places the vendor beside the companies that sell what it sells, rated with your methodology. They are the same peers as the Security posture page. The row shows how the peers’ ratings split, how the vendor’s current ratio and debt to worth compare with the peer median, a table of every company’s ratios and rating, and where each company sits in your bands. A company with no statements shows its Financial Health Score and stays out of the medians.Peer benchmarks
The Peer benchmark in the verdict, and the detail in Peers, place the vendor against companies of comparable industry and size. The cohort is named, along with how many companies are in it. If the page says a fallback cohort was used, the vendor’s own industry had too few scored peers and the percentile is against a broader set than the label suggests. Read it as directional.Adverse events
Dated, sourced events that moved the score, each with a link to what reported it. Severity decays with age, so an old event counts for less than a recent one of the same kind. Events awaiting review are shown but do not move the number. An event your team dismissed through a revision stops counting for your organization only.Comparability adjustments
When a stability floor or ceiling changed the score, the page says so under Caps, Floors and Guardrails in How the Score Is Built, with the reason and the before-and-after figures. A vendor floored at its class minimum and a vendor that earned the same number on its own signals are different situations, and a corrected score that looked like a computed one would hide that.Where the numbers came from
Open Sources and Documents. It lists every source behind the score with the date it was last seen, links out where a register publishes a stable per-company page, and the sources that were asked for and did not answer. A cap or floor applied by a hard rule, such as a bankruptcy filing, is listed with its reason under Caps, Floors and Guardrails. The documents your organization uploaded for the analysis are listed in the same row. Remove one there, or click Regenerate when the set has changed since the figures were computed.Where it shows up elsewhere
The score feeds the Financial health component of a Zero Touch Score, carrying its tier through as the component’s qualifier. If a vendor has no Financial Health Score, the Zero Touch component is left out of the composite rather than scored as zero. A vendor with no filed financials has not failed the component; it has no component.Read financial health from MCP or the API
You can read the score and the stability rating from an MCP client or with an API key. An MCP client reads withquery_vendors(kind="financial_health"), query_vendors(kind="financial_stability") and query_vendors(kind="financial_stability_peers"), and queues a peer refresh with mutate(entity="financial_stability_peers", action="refresh").
With an API key, use GET /v1/vendors/{vendor_id}/financial-stability, GET .../financial-stability/peers and POST .../financial-stability/peers/refresh. See Corporate family and financial stability. The fact sheet from GET /v1/vendors/{vendor_id}/fact-sheet carries a financials section.
Before an MCP client sends a write, it shows you the change and waits for you to confirm it. The MCP tool reference lists every field.
Troubleshooting
Related
Global financial coverage
The markets Coverbase reads filed statements from.
Security intelligence guide
The other outside-in score on the same vendor.
Corporate registrations guide
How a vendor is resolved to its filings.